Many professionals in Southlake, TX receive life insurance as part of their employer’s benefits package and assume it is enough. For most households, it is not. Employer-provided group policies typically pay one to two times your annual salary, a benefit that covers final expenses and perhaps a few months of living costs but falls well short of what a family carrying a seven-figure mortgage and raising children in Carroll ISD actually needs.
Supplemental life insurance exists precisely to close that gap. Whether purchased through your employer as a voluntary benefit or obtained privately as a standalone policy, it layers additional death benefit coverage on top of whatever you already have. Understanding how it works, what it costs, and who benefits most from it helps Southlake families make a more complete and deliberate decision about their financial protection.
Supplemental life insurance, also called voluntary life insurance, is additional coverage purchased on top of an existing policy. In the most common scenario, an employer provides basic group life insurance as a free or low-cost benefit, and then offers employees the option to purchase more coverage voluntarily. That additional purchase is the supplemental policy.
The term is also used more broadly to describe any individual policy bought privately to supplement whatever coverage exists elsewhere, whether through an employer, a previous policy, or a spouse’s plan. The common thread is that supplemental coverage adds to, rather than replaces, a baseline.
Supplemental coverage is typically term-based, providing a death benefit for a defined period. Some employers offer permanent coverage options as well, and accidental death and dismemberment riders can sometimes be added to extend the policy’s scope. The death benefit from supplemental coverage is paid in addition to any other life insurance payout, so a policyholder with both a $200,000 group policy and a $500,000 supplemental policy leaves beneficiaries with $700,000 in total coverage.
The average employer group life policy provides one to two times the employee’s annual base salary. Most plans cap out at $300,000 to $500,000 regardless of income, and they typically do not include commissions, bonuses, or other variable income in the calculation of the benefit.
For a Southlake household earning $200,000 per year with a $700,000 mortgage, two children heading toward college, and a lifestyle that depends on both incomes, a $200,000 employer death benefit covers less than one year of income. It does not pay off the mortgage. It does not fund four years of college for two children. It does not replace the income the surviving spouse was counting on for the next decade.
Financial professionals generally recommend total life insurance coverage of eight to ten times annual household income, sometimes more depending on debt levels and the number of dependents. For a Southlake family with $250,000 in household income, that target sits between $2 million and $2.5 million. Most employer group policies cover a fraction of that. Supplemental coverage, whether through the employer or privately, is the mechanism for closing the difference.
Supplemental coverage comes in several forms, and the right choice depends on the specific gap you are trying to fill and where you are in life.
Most workplace supplemental plans offer additional term coverage in multiples of salary, typically up to three to five times your annual pay or a defined dollar cap. Premiums are deducted directly from paychecks, making enrollment easy and payment automatic. A significant advantage of employer-based supplemental coverage is simplified underwriting: many plans allow employees to purchase up to $50,000 to $100,000 in additional coverage without answering health questions or undergoing a medical exam. Above those thresholds, full underwriting typically applies.
An individual term policy purchased outside of an employer relationship is also a form of supplemental coverage. These policies are fully portable, meaning they follow you through job changes, career transitions, and periods between employment. For healthy applicants, individual term policies often cost less than employer-based supplemental coverage because underwriting rewards good health with lower rates. Individual term policy also offers longer fixed-rate periods, typically 10, 20, or 30 years at a locked premium, rather than the age-banded structure of most group supplemental plans where rates increase every five years.
Many employer supplemental plans extend the option to purchase additional coverage on a spouse or partner, and sometimes on children. Spouse coverage is particularly valuable for dual-income Southlake households where the loss of either earner would significantly affect the household’s financial position. Child life coverage, while a sensitive topic, is typically purchased to cover final expenses and give the surviving family time to process a loss without the additional burden of immediate financial decisions.
Accidental death and dismemberment, commonly called AD&D, is a rider or standalone policy that pays an additional benefit if death or serious injury, such as loss of a limb or sight, results from a covered accident. AD&D is not a substitute for life insurance because it only pays for accidental causes. It is used as a supplement that provides an extra layer specifically for accident-related losses, which often occur without warning and leave families with no financial preparation time.
Final expense insurance, also called burial insurance, is a small permanent policy designed to cover funeral and end-of-life costs. The national median cost of a funeral exceeds $8,000, and total end-of-life expenses commonly reach $15,000 to $25,000 or more when medical bills are included. Final expense coverage ensures those costs do not fall on surviving family members at an already difficult time, without requiring them to draw down savings or go into debt.
The most important practical limitation of employer-based supplemental life insurance is that it is tied to your job. When you leave an employer, whether voluntarily or due to layoff, your supplemental coverage typically ends on your last day of employment or at month’s end.
Most plans offer two exit options: portability and conversion. Portability allows you to continue the same group coverage by paying premiums directly to the insurer, but without the employer’s group rate, premiums rise significantly. You also have a narrow window, typically 31 to 60 days from termination, to elect portability before the option closes permanently. Conversion allows you to convert the group term policy into an individual permanent policy, usually without new medical underwriting, but permanent policies cost substantially more than term coverage and may not be the right fit.
For Southlake professionals in fast-moving industries who may change employers every few years, or for anyone who values certainty about their coverage regardless of employment status, a privately purchased individual policy offers advantages that employer-based supplemental coverage cannot match. It belongs to you, not your job.
Supplemental coverage is not equally valuable for every household. It makes the strongest case for people in specific circumstances.
The choice between employer-based supplemental coverage and a privately purchased individual policy is not always one or the other. Many households benefit from both.
Employer-based supplemental coverage has three clear advantages: convenience, simplified underwriting for lower coverage amounts, and payroll deduction. It is easy to obtain during open enrollment, and for employees with health concerns, the guaranteed issue provisions can make it the only accessible source of additional coverage at standard rates.
Private individual policies have different strengths. They are fully portable, follow you through every job change, lock in premiums for the full term length rather than adjusting every five years, and can be sized to exactly what your household needs rather than what the employer plan allows. For a healthy 35-year-old Southlake professional, an individually underwritten term policy often costs the same or less than employer supplemental coverage at comparable benefit levels, with the added protection of ownership that does not depend on continued employment.
The most complete approach for most Southlake households is to accept any free or low-cost employer coverage, add employer-based supplemental coverage if it is cost-effective, and build the core of the household’s life insurance strategy on a privately held individual policy that is not at risk when employment circumstances change.
Life insurance, whether basic employer coverage, supplemental, or private, addresses the financial impact of your death on the people who depend on your income and contributions. It works alongside the rest of your household’s financial protection plan.
Homeowners insurance protects the physical structure and contents of your home from covered losses like fire, storm, and theft. Auto insurance covers your vehicles and the liability exposure that comes with driving. For renters, renters insurance covers personal property and personal liability independently of whatever coverage a landlord carries. Each policy covers a different risk, and none of them substitutes for life insurance.
An independent agency can review your full household coverage picture, assess whether your existing life insurance, supplemental or otherwise, matches your actual financial obligations, and compare options across multiple carriers. Barger & Associates serves families throughout Southlake, TX and across North Texas. Visit the areas we serve page to find coverage options across the DFW metro.
Yes, and for most Southlake households with significant financial obligations, this is the recommended approach. There is no rule limiting how many life insurance policies you can hold. Beneficiaries receive the combined total from all active policies. Many families carry an employer group benefit, an employer supplemental add-on, and a private individual policy simultaneously, sizing each to cover a specific purpose or time horizon.
It depends on the amount and the source. Employer group supplemental plans typically offer a guaranteed issue amount, often $50,000 to $100,000, that requires no medical exam and no health questions. Coverage above that threshold generally requires answering health questions or undergoing full underwriting. Private individual policies typically require underwriting, though some no-exam options exist for term coverage up to certain limits.
Employer-based supplemental coverage ends when your employment ends, unless you elect to port or convert the policy within the plan’s deadline, typically 31 to 60 days from termination. Portability allows you to continue group coverage at higher individual rates. Conversion allows you to switch from term to permanent coverage without new medical underwriting. Both options have strict deadlines and result in higher premiums. A privately purchased individual policy is not affected by job changes at all.
Calculate your household’s total coverage need first. Add your remaining mortgage balance, an income replacement figure based on years of support needed, estimated education costs for each child, and outstanding debts. Subtract any existing individual or group policy coverage from that total. The remainder is your coverage gap, and supplemental insurance is one way to fill it. A local agent can walk through those specific numbers with your household’s actual figures.
For employees with health conditions, employer group plans often offer better rates than private underwriting. For healthy individuals in their thirties and early forties, a privately purchased term policy can be equally or more cost-effective, particularly because private term locks in a level premium for the full 20 or 30-year term rather than increasing in five-year age bands as most employer supplemental plans do. Comparing the total cost over a ten-year period, including projected rate increases, is the most accurate way to evaluate the two options side by side.
Many employer supplemental plans offer dependent coverage, though the benefit amounts available for spouses and children are typically lower than those for employees. You usually must elect coverage for yourself before adding a spouse. Private individual policies can be sized to any amount and are not subject to the same caps. For a non-working spouse whose household contribution is significant, a private policy on that spouse is often the better option than a dependent rider through an employer plan.
Most supplemental life insurance policies cover the same causes of death as standard life insurance: natural illness, accidents, and all common medical causes. The standard exclusions apply: suicide within the contestability period, which is typically the first two years of the policy, and deaths resulting from fraud or material misrepresentation on the application. AD&D riders, which are sometimes bundled with supplemental plans, only pay for accidental causes and are not a substitute for full life coverage.
Barger & Associates is an independent insurance agency serving families, homeowners, and professionals across Southlake, TX and the broader North Texas area. As an independent agency, we compare life insurance options across multiple carriers to identify coverage that fits your household’s actual needs, not just what your employer’s plan happens to offer.
We conduct annual reviews to make sure your life insurance coverage, including any supplemental policies, stays aligned with your evolving household obligations. Whether you are filling a gap in employer coverage or building a complete household strategy from scratch, we are here to provide clear options and honest guidance.
If your employer’s life insurance is your only coverage, your family may be significantly underprotected. Contact Barger & Associates today by calling (972) 206-1234 or reaching out online. We will review your current coverage, calculate your household’s actual need, and compare supplemental and individual policy options across multiple carriers to build a strategy that protects what you’ve built here in Southlake.
Renters insurance cost in Texas averages around $20 per month statewide, but Southlake tenants often carry higher personal property values than the typical renter, particularly professionals relocating for corporate positions in the DFW corridor or leasing in the mixed-use communities near Southlake Town Square. That distinction matters when selecting policy limits. Barger & Associates has served Southlake renters from our office at 170 Players Cir since 2012, and our agents compare carriers across the market to identify coverage structures that reflect what policyholders here actually own.
Find out what renters insurance should cost for your specific situation in Southlake.
Renters insurance cost in Texas carries a distinct profile compared to most other states, shaped by three converging forces: the state's severe weather exposure to hail, tornadoes, and violent thunderstorms; elevated property crime rates in select submarkets; and the above-average personal property values tenants bring into high-income communities like those found across North Texas suburbs in Tarrant County. Policyholders in these markets are not shopping for a generic product. They are making a coverage decision that reflects real liability exposures and real asset values.
What follows covers the full scope of that decision. Our agents cover statewide cost benchmarks, the rating factors that move premiums up or down, and the specific market context that affects renters in the 76092 ZIP code, including the demand for premium rental properties in Southlake and the storm exposure created by proximity to Grapevine Lake. Tenants will also find guidance on policy limits, sublimits, and coverage gaps that a basic policy frequently leaves unaddressed. Barger & Associates, located at 170 Players Cir, Southlake, TX 76092, has been matching coverage structures to actual tenant needs across the region since our founding. areas served throughout Texas or contact our office to speak with a licensed agent.
Texas renters insurance premiums in 2026 typically fall between $15 and $30 per month, or roughly $180 to $360 annually, for a standard policy carrying $30,000 in personal property coverage and $100,000 in liability protection. That range reflects carrier data across the state and aligns with guidance published by the Texas Department of Insurance. Most tenants find that a basic policy costs less than a streaming subscription, yet covered losses without one can reach tens of thousands of dollars.
The $15 to $30 monthly figure assumes standard personal property limits, a typical deductible, and no scheduled endorsements for high-value items. Premiums shift based on the tenant's claims history, the age and construction type of the rental unit, and the specific perils included in the policy form. The Texas Department of Insurance recommends that policyholders complete a personal property inventory before selecting coverage limits, because underinsured tenants routinely find that covered losses fall short of actual replacement costs at the time of a claim. That inventory step is the single most effective way to confirm whether a $30,000 limit is adequate or whether higher limits are warranted.
Tenants renting in the 76092 ZIP code, particularly in luxury apartment communities and premium townhomes near Town Square, frequently carry personal property inventories that exceed the statewide benchmark by a meaningful margin. High-end electronics, jewelry, and designer furnishings common in this market push actual inventory values well above what a $30,000 limit covers, placing many local renters at the upper end of the statewide premium range or beyond it. A tenant in a high-end townhome near Southlake Boulevard should treat the statewide average as a floor, not a target. Our agents serving the DFW area consistently find that matching policy limits to an actual inventory produces materially different, and more accurate, coverage structures than defaulting to a standard limit.
What carriers charge Texas tenants in 2026 is calculated from several distinct variables, each of which carriers weight independently when underwriting a policy. Understanding these rating factors helps tenants make informed decisions about coverage structures rather than selecting the lowest quoted premium by default. The sections below address the three primary rating categories our agents evaluate when comparing policies for North Texas renters.
Personal property coverage limits define the maximum a carrier will pay for covered losses to a tenant's belongings, and the valuation method determines how that payment is calculated. Actual Cash Value (ACV) policies pay the depreciated value of a damaged or stolen item at the time of loss. A three-year-old laptop insured under ACV coverage will not be reimbursed at its original purchase price.
Replacement Cost Value (RCV) policies, by contrast, pay the amount required to purchase a comparable new item, closing the gap between the covered loss payment and the tenant's actual out-of-pocket replacement cost. RCV endorsements carry higher premiums, but for tenants in premium rental properties whose inventories include high-value electronics, furniture, or jewelry, the additional premium is typically justified by the reduced exposure at claim time.
Standard renters insurance policy limits in Texas include the $100,000 liability benchmark discussed above, which addresses bodily injury or property damage claims brought against a tenant. Tenants with pets, frequent guests, or above-average net worth should evaluate increasing that limit to $300,000 or adding a separate umbrella policy alongside their renters coverage for broader liability protection.
Deductible selection, typically ranging from $250 to $1,000, operates inversely to premium cost. A higher deductible reduces monthly premium but increases the tenant's out-of-pocket obligation when a covered loss occurs. Tenants should select a deductible aligned with their available liquid reserves, not simply the figure that produces the lowest quote.
Geographic peril exposure is a primary rating variable for carriers writing renters insurance policies across North Texas. Tarrant County sits within a corridor of above-average hail frequency and tornado activity, which elevates carrier loss ratios and directly influences premium calculations for renters in the area. Building construction type also affects underwriting: wood-frame structures carry different risk profiles than masonry construction, and older buildings may present additional vulnerability to storm-related perils.
Tenants near Grapevine Lake should note that a standard renters policy leaves out flood damage entirely, consistent with Texas Department of Insurance guidance. Flood coverage requires a separate policy, and that gap is not closed by any renters insurance endorsement.
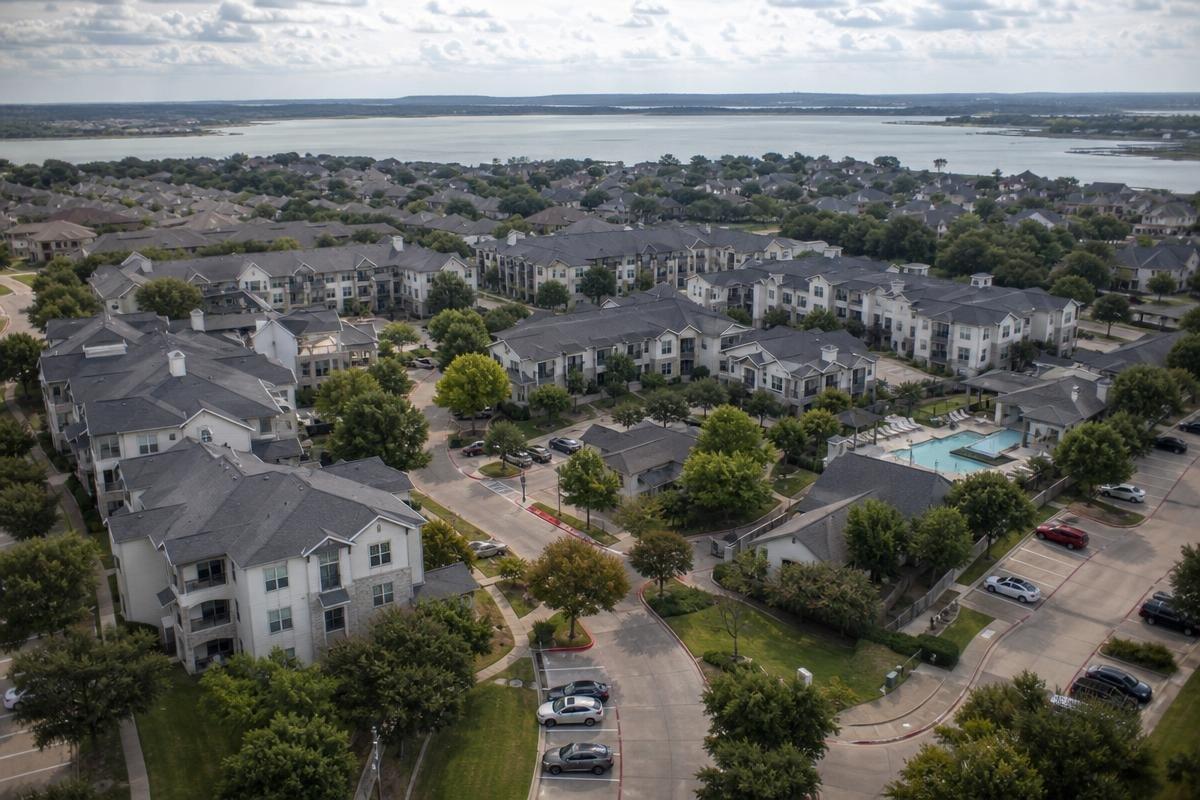
Texas law does not mandate renters insurance at the state level, but that legal silence does not protect uninsured tenants from financial exposure. Individual landlords and property management companies retain full authority to require renters insurance as a binding lease condition, and that practice is increasingly standard across Tarrant County's premium rental market. Luxury apartment and townhome communities in the DFW region, including gated properties in the Timarron area and along the Southlake Boulevard corridor, routinely include mandatory coverage clauses in standard lease agreements.
When a lease requires renters insurance, the tenant must provide a declarations page before the lease commencement date, typically naming the landlord or property management company as an interested party. This documentation confirms that a policy is active and that the interested party will receive notice of cancellation or material change. Our agents can issue proof of insurance documentation promptly after a policy is bound, which allows tenants to satisfy lease conditions without delay. Tenants can contact our office to confirm documentation requirements and bind coverage the same day.
A tenant without renters insurance bears the full financial burden of covered losses, including theft, fire damage to personal belongings, and liability claims arising from guest injuries on the premises. The landlord's property insurance covers the building structure only. It does not extend to a tenant's personal property or personal liability exposures, a distinction that produces significant financial hardship after a covered event. A renters policy is modest relative to that exposure, making an uninsured position a disproportionate financial risk for tenants carrying above-average personal property values.
Several proven strategies can reduce the cost of a renters policy without sacrificing the coverage structures that matter most. Tenants in the DFW area and across the broader Texas markets our agency serves often pay more than necessary simply because they have not reviewed available discounts with a licensed agent. Understanding which mechanisms carriers actually apply to premium calculations is the first step toward finding cheap renters insurance in Texas.
Carriers including Allstate extend multi-policy discounts when a tenant places both a renters policy and an auto policy under the same carrier. The discount varies by carrier and coverage structure, but the combined premium reduction is frequently meaningful enough to offset a portion of the auto rate. Bundling also creates a single point of contact for claims assistance, which simplifies the process when a covered loss involves both a vehicle and personal property. Tenants relocating to the DFW corridor from other markets should confirm whether their existing auto carrier offers a competitive renters bundle before purchasing policies separately.
Carriers evaluate building security infrastructure when calculating renters premiums. Deadbolt locks, monitored alarm systems, and in-unit or building-wide sprinkler systems each represent risk-reduction factors that can qualify policyholders for reduced rates. Tenants in gated communities common to the Southlake market, where premium townhomes frequently include monitored security systems, may already qualify for carrier discounts that have not been applied to their current policy. Confirming these features with an agent at renewal costs nothing and can produce a measurable reduction.
A clean claims history across the prior three to five years typically earns preferred pricing from most carriers. Raising the deductible from $250 to $500 or $1,000 also lowers the monthly premium, though policyholders should confirm their emergency reserves can absorb the higher out-of-pocket exposure before selecting a higher deductible. These adjustments, taken together, can bring premiums down to their lowest eligible tier for a given coverage level.
Our agents review available discounts against your specific coverage needs. Call (972) 206-1234 to find out which premium reductions apply to your renters policy.
A standard renters insurance policy carries an overall personal property limit, but that figure does not tell the full story. Most policies impose sublimits on specific property categories, meaning the policy will only pay up to a defined dollar amount for that category regardless of the total coverage elected. Tenants carrying high-value personal property need to understand where those sublimits apply before a loss occurs, not after.
Jewelry, watches, fine antiques, firearms, and electronics commonly carry sublimits ranging from $1,000 to $2,500 within a standard renters policy. A tenant with a $10,000 engagement ring, for example, would receive no more than $1,500 to $2,500 under most base policy structures, even if the overall personal property limit is $50,000. Families relocating to the DFW area for executive positions often arrive with luxury watches, fine jewelry, or collectibles that far exceed these default sublimits. The appropriate solution is a Valuable Personal Property Coverage endorsement, which schedules individual items at agreed or appraised value and removes the standard sublimit restriction.
Loss of use coverage pays for temporary housing and additional living expenses when a covered peril renders a rental unit uninhabitable. Standard renters policies typically set this provision at 20 to 30 percent of the elected personal property limit. A tenant carrying the $30,000 baseline discussed above would receive between $6,000 and $9,000 in loss of use benefits, which may fall short of temporary housing costs in a higher-rent market like Southlake. Tenants should verify this provision is included in their policy and confirm the limit is adequate relative to current local rental rates before assuming the coverage is sufficient.
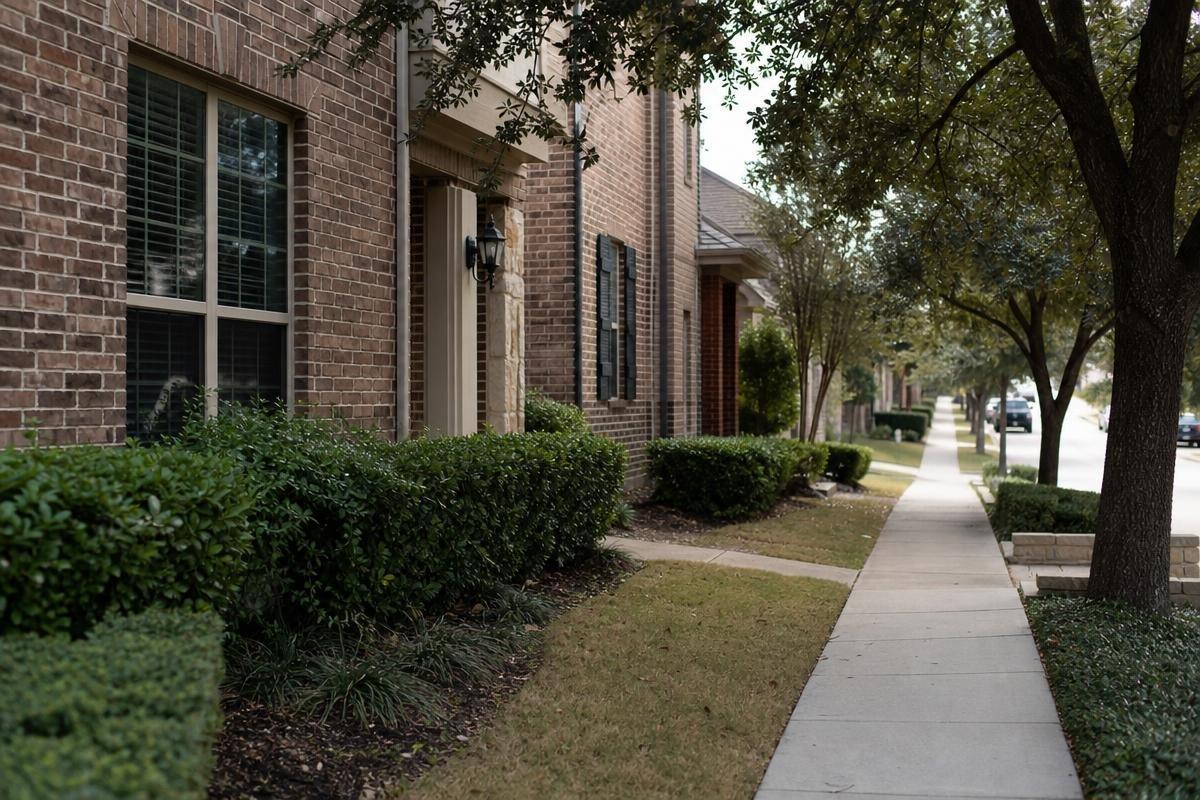
The ZIP 76092 rental market draws a distinct tenant profile. Families relocating for the highly rated Carroll ISD school district frequently lease townhomes and single-family rentals while their permanent homes close or are built. These households carry above-average personal property values, including high-end electronics, jewelry, and professional equipment, that far exceed the coverage limits built into a basic policy. A tenant renting near the Town Square district with $80,000 in personal property needs a materially different coverage structure than the statewide average tenant profile suggests. Our agents, based at 170 Players Cir, have worked directly with this tenant profile for more than a decade. Tenants who also operate home-based businesses from their rental unit should review our homeowners and renters insurance options in Southlake, as a standard renters policy leaves out most business property and liability exposures.
The DFW corridor, including the communities of Colleyville and Keller that border this area, sits in a region with above-average hail and severe thunderstorm frequency. Standard renters policies cover personal property damaged by wind and hail inside the rental unit. The building envelope, including the roof, exterior walls, and windows, falls under the property owner's policy, not the tenant's. Policyholders should confirm their renters policy includes coverage for water intrusion that follows a storm event, as this distinction matters significantly when a damaged roof allows rain into a unit.
Tenants renting near the Grapevine Lake shoreline face an additional exposure that a renters policy does not address. Portions of the 76092 ZIP code carry FEMA-designated Special Flood Hazard Areas, generally the Zone AE mapping that follows the lake shoreline and the drainage channels feeding into it, while most of the surrounding higher ground sits in lower-risk Zone X. Because ground-level flood damage from rising water is excluded from standard renters coverage, tenants in or near a mapped flood zone need a separate policy, available either through the National Flood Insurance Program (NFIP) or through private flood carriers that an independent agent can access on your behalf.
Our agents can pull the FEMA flood zone designation for a specific rental address and quote a supplemental flood policy where one is warranted. Contact our office to confirm your flood exposure before the next storm season arrives.
The average renters insurance cost in Texas runs between $15 and $30 per month for a standard policy in 2026. Premiums shift based on coverage limits, deductible selection, location, and prior claims history. Tenants in higher-value rental communities may see quotes toward the upper end of that range, particularly where personal property inventories exceed typical statewide averages.
A standard renters policy covers personal property against fire, theft, vandalism, and wind or hail damage to belongings inside the unit. It also includes personal liability protection and loss of use coverage if the unit becomes uninhabitable after a covered loss.
State law does not require renters insurance, but landlords may impose it as a lease condition, which is common in luxury rental communities across the DFW region. Tenants should review lease terms before move-in. Our agents can bind coverage quickly and issue proof of insurance the same day in most cases.
Standard renters policies do not cover flood damage from rising water, storm surge, or surface water intrusion. The Texas Department of Insurance explicitly identifies this gap in its consumer guidance. Tenants in flood-prone areas should evaluate an NFIP policy or a private flood policy to address this exposure.
The right renters insurance policy limit depends on the full replacement cost of all belongings. A written home inventory using replacement cost value methodology is the most reliable method for determining an adequate limit. Tenants in townhomes and single-family rentals near top-rated school districts often find that standard $30,000 limits fall short of their actual inventory values.
Bundling renters insurance with an auto policy through the same carrier typically produces a multi-policy discount that reduces the overall premium on both policies. As an Allstate agency, our team offers bundling options for policyholders throughout the region. Contact our team to review your coverage options and identify discount opportunities across your policies.
Renters across Keller, Colleyville, and the broader DFW area deserve coverage structures built around their actual inventory values and liability exposures, not a generic policy pulled from a comparison website. Our team at 170 Players Cir in Southlake reviews individual coverage needs, identifies sublimit gaps, and matches policyholders with the right protection provisions for their rental situation. Call (972) 206-1234 to schedule a coverage review, or reach out through our contact page to get started.
Call (972) 206-1234 to speak with our team directly. We're ready to answer your questions, walk you through your options, and help you find the right solution for your needs. Whether you're just starting to plan or ready to move forward, we'll make the process simple and stress-free.
Reach out today and let's talk about how we can help.
Windstorm insurance in Texas is not a single product with a single source, and Southlake homeowners face a coverage structure that differs significantly from what coastal property owners encounter. Because Tarrant County sits outside the Texas Windstorm Insurance Association's eligible territory, private carriers are the only path to wind and hail protection on Southlake residences. Our agency, founded in 2012 and serving homeowners throughout Texas, evaluates private market options to identify coverage structures that address the real storm damage exposures North Texas properties carry.
Not sure whether your policy still covers wind and hail? Have a Southlake agent read your declarations page before storm season. Call (972) 206-1234.
Windstorm coverage in Texas operates through two structurally different channels, and which one applies depends entirely on where the insured property sits. Coastal properties in designated catastrophe counties may qualify for coverage through the Texas Windstorm Insurance Association (TWIA). Inland properties obtain their storm protection through private carriers. That geographic distinction, established once here, shapes every coverage decision this article addresses.
Because Southlake sits inland, homeowners carrying homeowners insurance in Southlake rely on private market carriers for their storm damage coverage. Some of those same homeowners also own vacation or investment properties in Galveston, Corpus Christi, or Port Aransas, where TWIA windstorm insurance becomes directly relevant. What follows covers both audiences, covering TWIA eligibility geography, covered perils, WPI-8 certification requirements, cost drivers, and how to compare private wind and hail endorsements for inland properties.
Barger & Associates, founded in 2012 by Joshua Barger and based at 170 Players Cir, Southlake, TX 76092, has guided homeowners across the region through exactly these coverage decisions. Call (972) 206-1234 to review windstorm coverage options with our team today.
Windstorm protection in Texas is delivered through two channels that are not interchangeable. Private carriers may include wind and hail coverage within a standard HO-3 homeowners policy or attach it as a separate endorsement, depending on the property's location and the carrier's underwriting guidelines. The Texas Windstorm Insurance Association, commonly called TWIA, is a state-created residual market mechanism established by the Texas Legislature and regulated by the Texas Department of Insurance. TWIA exists exclusively for properties in 14 designated catastrophe counties along the Gulf Coast that cannot obtain private windstorm coverage.
As noted above, Tarrant County is not among those catastrophe counties, so a Southlake homeowner will never bind a TWIA policy on a local residence. The practical consequence is that all of your leverage lives in the private market: which carrier you choose, which endorsement form applies, and which deductible you accept. Homeowners who also own coastal investment properties in Galveston or Corpus Christi may need TWIA coverage for those assets while carrying private wind coverage on their primary residence.
A windstorm policy covers direct physical damage caused by wind, hail, and wind-driven rain that enters a structure through a wind-created opening. These are the losses most policyholders associate with severe storm events. What the policy does not cover is equally important: flooding, storm surge, and water intrusion from sources other than a wind-created breach all require a separate flood policy through the National Flood Insurance Program or a private flood carrier. Fire following a windstorm event is typically addressed under the homeowners policy, not the windstorm coverage itself, which is a common source of confusion during the claims process.
Policyholders reviewing their coverage should confirm whether windstorm perils are included in their current homeowners policy or excluded by endorsement. Our team evaluates those policy provisions in detail for homeowners across the region.
The Texas Windstorm Insurance Association is a state-created insurer established by the Texas Legislature to provide windstorm and hail coverage to coastal property owners who cannot obtain protection through the private market. TWIA does not operate on state tax dollars. It is funded through policyholder premiums, reinsurance contracts, and catastrophe bonds, with the Texas Department of Insurance overseeing its rates, rules, and financial solvency. Understanding TWIA's structure matters to any homeowner evaluating windstorm coverage across the state, whether for a primary residence or a Gulf Coast vacation property.
TWIA exists because private carriers largely exited coastal Texas markets following Hurricane Alicia in 1983 and subsequent damaging storm seasons. As insurers withdrew, coastal property owners lost access to affordable wind and hail protection. The association stepped in as the insurer of last resort, meaning TWIA windstorm insurance is available only to property owners who have been denied coverage by private carriers. It is not a first-choice market and was never intended to compete with private insurers on price or policy flexibility.
TWIA eligibility is strictly geographic. Only properties located in the following 14 designated catastrophe counties qualify for a TWIA policy: Aransas, Brazoria, Calhoun, Cameron, Galveston, Jefferson, Kenedy, Kleberg, Matagorda, Nueces, Refugio, San Patricio, Willacy, and a defined portion of Harris County. Inland counties, including Tarrant, Collin, and Denton, are not eligible. Homeowners in Plano, Frisco, and McKinney fall entirely outside TWIA's geographic scope and must secure windstorm coverage through private carriers. Southlake homeowners who also own vacation properties in Galveston or along the Nueces County coast should evaluate TWIA eligibility separately for those coastal assets.
TWIA policies carry defined maximum coverage limits. As of 2026, residential dwellings are insurable up to $1.77 million, personal property up to $375,000, and commercial structures up to $4.424 million. These figures are published by TWIA and should be confirmed at twia.org before binding coverage. Policies also carry separate wind deductibles, typically calculated as a percentage of the insured dwelling value. On a high-value coastal property, that percentage-based deductible represents a significant out-of-pocket exposure before coverage responds to a covered loss.
Texas law does not universally require windstorm insurance statewide. The mandate, where it exists, comes from mortgage lenders rather than state statute. Homeowners in TWIA-eligible coastal counties routinely face lender-mandated windstorm coverage as a condition of loan origination, structured similarly to how flood insurance is required in FEMA Special Flood Hazard Areas.
In counties such as Galveston and Nueces, lenders treat windstorm coverage as a prerequisite before closing. Allowing that coverage to lapse triggers a force-placed insurance provision. Force-placed policies typically carry higher premiums and narrower coverage provisions than a voluntary policy obtained through TWIA or a private carrier. Homeowners who own vacation or investment properties along the Gulf Coast while residing inland must maintain separate windstorm coverage on those coastal properties regardless of what their local policy provides.
For homeowners in Tarrant County communities, hail and wind exposure is typically insured within a standard HO-3 homeowners policy. However, policyholders must review their declarations page carefully. Insurers have begun excluding these perils from standard policies in high-risk zip codes following severe hail seasons across the DFW region. When that exclusion appears at renewal, a separate endorsement or standalone policy becomes necessary to maintain full storm damage protection.
This is a gap that surfaces most often at renewal, not at the time of purchase. In Southlake, where custom homes in the Carroll ISD corridors and around Southlake Town Square routinely appraise well into seven figures, an undetected exclusion is not a rounding error, it is a six-figure repair bill left uninsured. Our agents review declarations pages line by line to catch these shifts before a covered loss is denied.
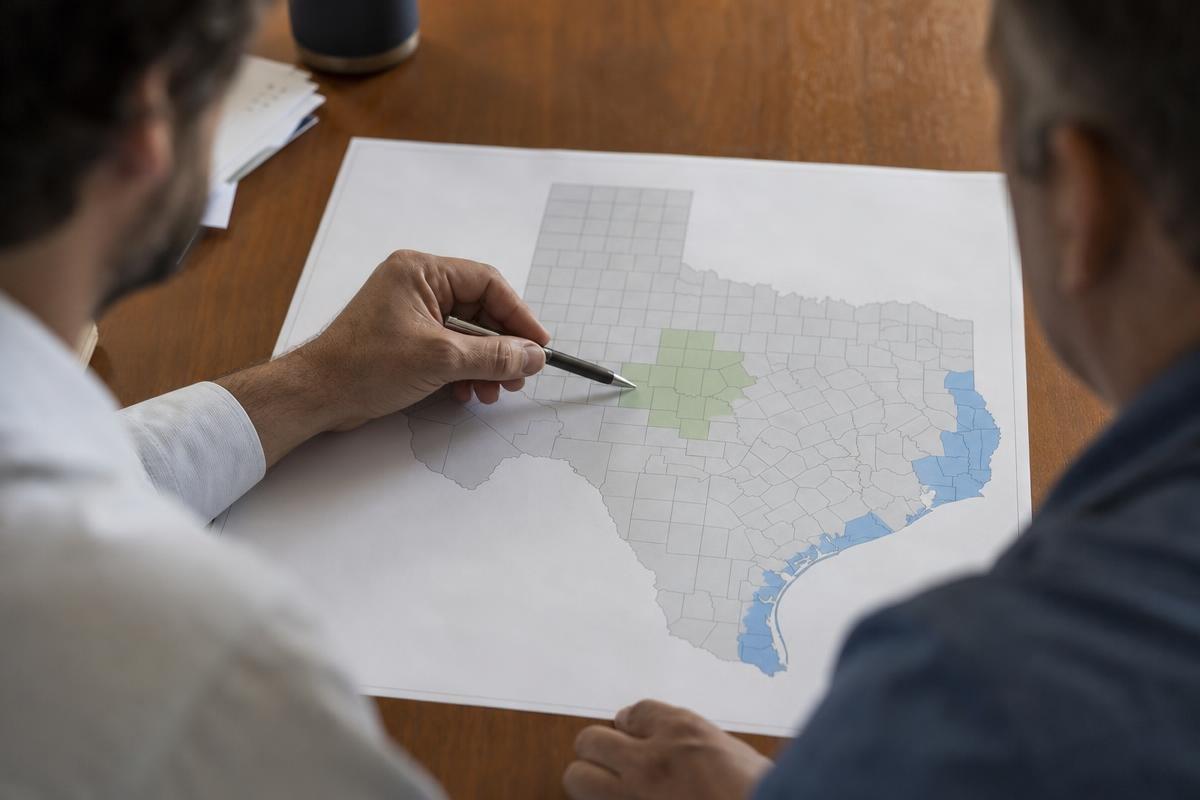
Properties located in TWIA-eligible coastal counties cannot be insured through the Texas Windstorm Insurance Association without a valid WPI-8 certificate. The WPI-8, formally known as the Windstorm and Hail Inspection Certificate, is issued by the Texas Department of Insurance and confirms that a structure was built or improved in compliance with the windstorm building code applicable to first-tier coastal counties. For Southlake homeowners who also own vacation or investment properties along the Gulf Coast, a missing WPI-8 is a coverage gap that can leave a coastal property entirely uninsurable through TWIA.
The WPI-8 certificate attaches to the structure itself, not to the property owner. Ownership transfers do not void the certificate; it conveys with the property at closing. Structures constructed before September 1, 1971 in certain TWIA counties may qualify under a grandfather provision, but any post-1971 construction or renovation requires a valid inspection on record. Homeowners purchasing existing coastal properties should request the WPI-8 certificate as a standard item in due diligence. If the certificate is lost or cannot be located, the Texas Department of Insurance maintains a WPI-8 Certificate Lookup tool at twia.org that allows searches by property address.
Only TDI-authorized inspectors, not general home inspectors or licensed contractors, are permitted to conduct WPI-8 inspections. The inspection must occur during construction or renovation, not after the fact. Homeowners who discover after project completion that no authorized inspector was engaged during the build may find that TWIA windstorm insurance coverage is unavailable for that structure. This is one of the most common and costly oversights affecting coastal property owners. Our agents work with homeowners across the DFW area who hold coastal properties, helping identify WPI-8 compliance gaps before they become an uninsured loss.
Own a coastal property in Galveston, Corpus Christi, or Port Aransas? Our agents can verify your WPI-8 status and TWIA eligibility before a covered loss exposes the gap.
Windstorm insurance premiums vary significantly depending on whether a property sits in a TWIA-eligible coastal county or an inland area where private carriers set their own rates. No single price applies across the state. Premium structures reflect location, construction type, roof condition, coverage limits, and deductible provisions selected at the time of binding.
TWIA rates are established by the Texas Department of Insurance commissioner and applied uniformly by county and construction class. This is not a competitive market. Insurers do not bid against each other for coastal wind business through TWIA. Key rating factors include county of location, construction type (wood frame versus masonry), year built, distance from the coast, selected coverage limits, and the deductible percentage. First-tier counties, those closest to the Gulf, carry higher base rates than second-tier counties farther inland.
Deductible provisions deserve careful attention. TWIA policies typically carry a percentage-based wind deductible rather than a flat dollar amount. On a $500,000 coastal property, a 2% deductible represents a $10,000 out-of-pocket obligation before covered losses are paid. TWIA premiums have increased across recent legislative sessions as the association works to maintain actuarial soundness against growing storm exposure along the Gulf Coast.
Homeowners in Flower Mound, Denton, and surrounding communities carry their storm coverage through private carriers, typically embedded within the overall homeowners policy. Our agents see premium structures shaped by roof age, roofing material, claims history, zip code loss experience, and selected coverage limits. Impact-resistant Class 4 roofing can qualify for meaningful discounts with certain carriers, which is worth weighing on a re-roof decision.
When you compare private options, the differences that matter are rarely the headline premium. Look instead at how each carrier writes the deductible (flat dollar versus a 1% or 2% percentage), whether roof losses are settled at replacement cost or actual cash value on aging shingles, and whether cosmetic hail damage is excluded by endorsement. Two policies at the same price can produce a $10,000 difference in what you actually recover after a hailstorm.
The DFW metroplex sits within one of the most active hail corridors in the United States. Actuarial literature identifies this corridor, stretching from central Texas through the plains states, as "Hail Alley." For homeowners in communities like Flower Mound, Frisco, and the broader Metroplex, this geographic reality has direct consequences on how private carriers structure coverage at renewal. Because inland Texas has no residual market equivalent to TWIA, local homeowners depend entirely on the private market for storm protection.
North Texas has a documented history of catastrophic hail. The April 2021 hailstorm that struck Fort Worth and northern Tarrant County produced baseball-sized hail and drove insured losses well into the hundreds of millions of dollars, and the March 2016 storm that hit Wylie and northern Collin County remains one of the costliest single hail events in state history. Events like these are why carriers now commonly introduce percentage-based deductibles, wind sublimits, or in some cases outright exclusions, particularly on homes with roofs 15 or more years old or with wood shake roofing materials.
A percentage-based deductible carries real financial weight in a high-value market. Southlake's median home value generally runs in the $900,000 to $1.2 million range, and many custom homes exceed that considerably. On a home valued at $1 million, a 2% deductible produces a $20,000 out-of-pocket obligation before coverage responds to a covered loss. Policyholders who have not reviewed their declarations page recently may be unaware that their deductible structure changed at the last renewal cycle.
Policyholders should locate the "Perils Insured Against" section of their HO-3 policy declarations and confirm that these perils appear as covered without sublimits or separate deductible schedules. If a separate storm deductible is listed, it will typically appear as a percentage rather than a flat dollar figure.
Discovering a coverage gap after a loss event is far more costly than identifying it during a policy review. Our agents conduct thorough reviews to catch these gaps before a storm season arrives, the same way we examine coverage gaps that cost Southlake homeowners and business owners money across multiple policy types.
For homeowners evaluating their full coverage structure, our home insurance options in Frisco and surrounding Metroplex communities reflect the same carrier market and renewal pressures facing policyholders across the region. Call (972) 206-1234 to schedule a policy review.
TWIA windstorm insurance and private windstorm endorsements cover direct wind damage from hurricanes, including structural damage caused by high winds and wind-driven rain. Storm surge and inland flooding are explicitly excluded under both TWIA policies and standard homeowners forms. Coastal property owners in areas such as the Galveston Bay shoreline or the Coastal Bend should carry a separate flood policy through the National Flood Insurance Program or a private flood carrier alongside their windstorm coverage.
No. The Texas Windstorm Insurance Association only writes policies for properties located in one of the 14 designated catastrophe counties, all of which are along the Gulf Coast. Inland counties are outside TWIA's eligibility boundary entirely. Homeowners in the DFW region must obtain wind and hail protection through private carriers, either within an HO-3 policy or through a separate endorsement. Our agents can review your homeowners policy to confirm whether these perils are included or excluded.
A standard deductible is a fixed dollar amount applied to most covered losses. A wind/hail deductible is calculated as a percentage of the insured dwelling value, commonly 1% to 2%. On a home insured for $900,000, a 2% deductible means the policyholder absorbs the first $18,000 of any qualifying loss before the policy responds. High home values in the Southlake market make this distinction especially significant at renewal.
Most HO-3 policies include these perils under the Perils Insured Against section, but not all do. Insurers active in high-frequency hail markets across the northern DFW corridor have begun excluding them or applying separate percentage deductibles at renewal without prominent notice. Policyholders should review their declarations page and policy form annually to confirm coverage has not been restructured.
Barger & Associates, founded in 2012 by Joshua Barger, conducts policy reviews for homeowners throughout the state, including those with both inland residences and Gulf Coast vacation or investment properties. Our office at 170 Players Cir, Southlake, TX 76092 serves homeowners in Flower Mound, the Grapevine area, Fort Worth, Houston, and communities across the state. Hail seasons across the northern DFW corridor and Gulf Coast storm exposure both create coverage gaps that a standard policy review can identify before a loss occurs. Call (972) 206-1234 to schedule your coverage review today.
Call (972) 206-1234 to speak with our team directly. We're ready to answer your questions, walk you through your options, and help you find the right solution for your needs. Whether you're just starting to plan or ready to move forward, we'll make the process simple and stress-free.
Reach out today and let's talk about how we can help.
Whole life insurance cash value is the savings component that accumulates inside a permanent life policy, growing on a tax-deferred basis throughout the life of the contract. Barger & Associates, an independent agency founded in Southlake in 2012, compares multiple carriers to help policyholders across Texas select whole life structures with strong guaranteed cash growth and dependable death benefit protection. Our team explains how premiums are allocated, how guaranteed values build year over year, and how funds can be accessed when needed.
Call (972) 206-1234 to review whole life options with our Southlake team.
Most policyholders recognize that whole life insurance includes a savings component, yet few understand how the guaranteed cash value actually accumulates or how it functions as a long-term financial asset. The permanent life insurance cash value sitting inside a policy can serve as collateral, supplement retirement income, or fund major expenses, but only when policyholders understand the underlying mechanics. This article explains how whole life insurance cash value builds over time, what realistic accumulation timelines look like, the methods available to access funds, and the tax treatment that applies under current federal rules.
Barger & Associates is an independent agency founded in 2012 and based at 170 Players Cir in Southlake, serving policyholders throughout Texas. Our team compares multiple carriers to match permanent life coverage with the financial obligations Texas families carry, including mortgage balances, college tuition projections, and everyday living costs that survive the loss of an income earner.
The sections that follow cover four content pillars: the accumulation mechanics that drive guaranteed cash value growth, the realistic timeline policyholders should expect before meaningful values appear, the methods used to withdraw money or borrow against the policy, and the tax treatment that distinguishes whole life from other savings vehicles available across the state.
Whole life insurance cash value is the tax-deferred savings component built into a permanent life insurance policy, funded by a portion of each premium payment and growing at a guaranteed rate fixed by the carrier at policy issue. Unlike term coverage, which expires without residual value, permanent life insurance cash value accumulates over the life of the contract and remains accessible to policyholders through loans, withdrawals, or surrender. Throughout Texas, policyholders use this internal account as a long-term financial asset alongside the death benefit.
Each premium payment is divided into three defined allocations specified in the policy document at issue: the cost of insurance, administrative expenses, and the cash value contribution. The cost of insurance funds the carrier's mortality risk, administrative charges cover policy maintenance, and the remaining portion is credited to the cash value account. This allocation structure is contractually disclosed, allowing policyholders across the state to verify exactly how their dollars are applied.
Guaranteed cash value life insurance contains a contractually fixed schedule, displayed in the policy's cash value table, showing the minimum account balance at each policy anniversary. Dividend cash value, by contrast, is available only on participating policies issued by mutual or mutual-style carriers and is not guaranteed in any given year. For Texas policyholders weighing participating versus non-participating products in the regional market, dividend options typically include increasing cash value, reducing future premiums, or purchasing paid-up additional insurance that further compounds the account.
The carrier credits guaranteed interest to the cash value account on a defined schedule, with participating contracts adding non-guaranteed dividends when declared by the board. Under Internal Revenue Code provisions, this internal growth is tax-deferred, meaning policyholders are not taxed annually on accumulated gains, a treatment that separates whole life from standard taxable savings accounts.
Our independent agency compares multiple carriers throughout the region to help policyholders read the projected versus guaranteed columns side by side before binding coverage. That comparison is where the long-term value of a policy is genuinely determined.
Whole life insurance cash value follows a predictable, slow-then-steep trajectory shaped by carrier expense structures, mortality charges, and compounding dividends. Policyholders across the DFW area, from Fort Worth to Frisco, often misread early-year statements because the surrender value appears disproportionately low relative to premiums paid. Understanding the standard growth curve helps owners evaluate whether a policy is performing as illustrated at issue.
The first decade carries the heaviest expense load. Carriers front-load acquisition costs, agent commissions, and underwriting expenses into years 1 and 2, which is why surrender value often shows pennies on the dollar against premiums paid. Surrender charge schedules vary by carrier, but most decline gradually through year 10.
By years 5 through 10, guaranteed cash value life insurance contracts typically show measurable accumulation, and dividend-paying mutual policies begin layering non-guaranteed credits on top of the contractual floor. This is the phase where Dallas and Plano policyholders frequently consider lapsing, often without recognizing what comes next.
Mortality costs stabilize and the compounding curve accelerates noticeably during this window. Surrender charges have fully eroded by year 11 on most contracts, meaning each premium dollar contributes more directly to cash value rather than offsetting internal expenses.
Paid-up additions riders become particularly useful tools during this stage, allowing policyholders to direct additional premium toward small, fully paid blocks of insurance that immediately generate their own cash value and dividends. Frisco and Fort Worth clients reviewing legacy contracts often discover unused PUA capacity that can materially change the trajectory.
Many contracts reach paid-up status at year 20, year 30, or a specified attained age, commonly 65 or 121 under modern policy design. Paid-up status means no further premiums are required, while cash value and death benefit continue to grow under the contract's guaranteed and dividend provisions.
Mature cash value can fund retirement income through policy loans or withdrawals, cover large expenses, or pass as a tax-advantaged inheritance. Our team reviews legacy policies for Texas policyholders across the region, comparing current cash value position against the original in-force illustration and outlining whole life and permanent coverage options available through multiple carriers.
Wondering whether your existing policy is tracking on schedule? Call (972) 206-1234 for a policy review.
Policyholders can access accumulated funds through three primary methods: policy loans, partial surrenders or withdrawals, and applying the cash value toward future premiums. Each method carries distinct tax consequences and affects the death benefit differently, which is why we walk every client through the implications before they sign paperwork. Our independent agency compares multiple carriers across Texas, and we apply that same diligence when advising on access strategies.
Whole life insurance policy loans allow policyholders to borrow against accumulated cash value without a credit check, since the cash value itself serves as collateral. The loan is not a taxable event while the policy remains in force, and repayment terms are flexible. However, unpaid interest compounds and is added to the loan balance, which reduces the death benefit paid to beneficiaries.
A policy lapse with an outstanding loan balance above the cost basis can trigger ordinary income tax on the gain. Clients funding a home purchase in Plano or covering tuition at UT Austin often choose loans because the funds remain accessible without surrendering coverage.
A partial surrender permanently reduces both the cash value and the death benefit. Understanding how to withdraw money from life insurance starts with the cost basis, which is the total of premiums paid into the policy. Amounts withdrawn up to basis are received income-tax-free, while amounts above basis are taxed as ordinary income at the policyholder's marginal rate.
A full surrender returns the accumulated cash value minus any surrender charges and outstanding loan balances. Gain above basis is again taxed as ordinary income, and the coverage terminates entirely. For policyholders in DFW evaluating cash value life insurance Texas options, this is rarely the preferred route when alternatives exist.
Once sufficient funds accumulate, the insurer can apply the cash value balance toward future premium obligations. This premium offset arrangement is useful during periods of income disruption, retirement transition, or business cash-flow gaps. It does, however, extend the time required to reach paid-up status and slows long-term cash value growth.
Coverage planning across the region often pairs life insurance strategy with property protection questions, and clients reviewing what renters insurance actually covers in Southlake frequently raise similar questions about how policy structures interact. Call (972) 206-1234 to review access options with our team.
Permanent life insurance cash value receives favorable federal tax treatment under specific provisions of the Internal Revenue Code. Policyholders throughout Texas should understand these rules when evaluating whole life contracts alongside other long-term assets. The following information is educational and does not constitute tax advice; consultation with a qualified tax advisor is recommended before relying on any particular treatment.
Under IRC Section 7702, life insurance contracts that meet statutory definitions receive tax-deferred treatment on internal cash value growth, meaning annual increases are not reported as taxable income to the policyholder. This allows guaranteed cash value to accumulate without yearly tax drag, a structural advantage relative to many taxable investment accounts held across the state.
IRC Section 101(a) generally provides that death benefits paid to named beneficiaries are received income-tax-free. Transfer-for-value rules, estate inclusion, and ownership arrangements can alter this treatment, so coordination with a tax professional is important when structuring beneficiary designations or trust ownership.
Guaranteed cash value functions as a floor of liquid, market-risk-free assets that complements retirement accounts, brokerage portfolios, and real estate held by policyholders throughout the region. For families addressing mortgage obligations, college tuition planning, or estate transfer to the next generation, cash value life insurance Texas residents purchase can stabilize the conservative allocation of a broader plan.
Barger & Associates has served Texas policyholders as an independent agency since 2012. From the 170 Players Cir office, our agents review coverage structures for clients in Keller, Colleyville, Grapevine, Flower Mound, and statewide markets including Austin, Houston, and San Antonio. Whole life coverage reviews examine guaranteed values, dividend history when applicable, and integration with existing protection provisions.
Policyholders evaluating new whole life coverage, or reviewing the cash value position of an existing contract, can reach Barger & Associates at (972) 206-1234 to schedule a coverage review. Our agents will walk through the policy's cash value schedule and how the contract fits within a broader financial plan.
In Texas, the cash value of a whole life policy is generally counted as an asset when determining Medicaid eligibility, which could affect qualification for long-term care benefits. If your policy's cash surrender value exceeds the asset limit, you may need to spend it down or explore exempt asset strategies before applying. Barger & Associates recommends consulting with a licensed advisor before making any changes to your policy for Medicaid planning purposes, as the rules are complex and highly individual.
No. One of the defining features of a whole life policy is that you cannot be denied a loan against your available cash value, regardless of your credit score or financial situation. The insurance carrier simply uses the cash value as collateral, and no credit check is required. This makes policy loans a reliable option in financial emergencies when other credit sources may not be accessible.
In most traditional whole life policies, the insurance carrier retains the accumulated cash value and pays out only the stated death benefit to beneficiaries. This is a common point of confusion for policyholders who assume the death benefit and cash value stack on top of each other. Some policies, called "increasing death benefit" or "option B" policies, do pay out both, but they typically carry higher premium costs. Barger & Associates can help you review your policy structure to confirm exactly what your beneficiaries will receive.
Texas has exceptionally strong creditor protection laws for life insurance cash value, making it one of the most favorable states in the country for this purpose. Under the Texas Insurance Code, cash value and death benefits are generally exempt from claims by most creditors, including in bankruptcy proceedings. This protection does not typically extend to fraud or certain domestic support obligations, so Barger & Associates advises confirming the specifics with a legal professional alongside your insurance review.
A 401(k) typically offers higher growth potential through market-linked investments, while a whole life policy provides guaranteed, conservative growth with no market risk and a built-in death benefit. Contributions to a 401(k) are pre-tax but withdrawals are taxed as ordinary income, whereas cash value grows tax-deferred and loans are generally not treated as taxable income. Most financial advisors, including the team at Barger & Associates, treat whole life insurance as a complement to retirement accounts rather than a direct replacement.
The guaranteed credited rate is fixed at the time the policy is issued and will not decrease, which protects policyholders from interest rate fluctuations over time. However, if your policy participates in dividends, the dividend rate is declared annually by the carrier and can vary based on the company's financial performance. Most major mutual insurers have maintained consistent dividend payments for decades, but dividend amounts are never contractually guaranteed. Barger & Associates can walk you through historical dividend performance for specific carriers before you commit to a policy.
Many term policies include a conversion rider that allows you to switch to a permanent whole life policy without a new medical exam, but term policies carry no cash value to transfer since they are pure death benefit coverage. Once converted, your new whole life policy begins accumulating cash value from the date of conversion, and the growth timeline starts fresh. The conversion deadline and available permanent products vary by carrier, so it is important to review your term policy documents with Barger & Associates before that window closes.
Call (972) 206-1234 to speak with our team directly.